WHAT eID IS
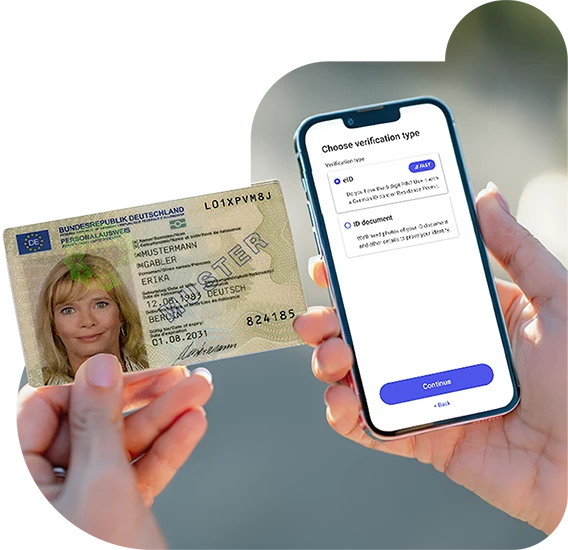
Verified identity data
From a government or bank source
Available at high assurance level
Substantial or high LoA, depending on the scheme; both satisfy AMLR
One approval from the user
Replaces the document upload
An AMLR default route
From 10 July 2027
WHAT eID ISN’T
The EUDI Wallet
Where a strong national eID exists, the EUDI Wallet is being built on top of it
Proof of liveness
Confirms the identity, but not the person
AML screening
Sanctions and PEP checks still may be needed
Always high assurance level
Check the LoA, scheme by scheme, as not all eIDs are substantial or high LoA
Universal
Adoption varies per country. Only effective where there is real adoption.
Document check
Capture front
Capture back
Selfie
Liveness
Review
Identity verified
Five steps for the user. Verification starts from zero, every time.
eID check
Verified when eID was issued
Customer approves
Identity verified
Verified already. Customer just approves.
Before they reached you
In your funnel
Outcome
The identity work still happens. It just doesn’t happen in your funnel. A bank or a government did it and you get the answer, not the workload.
Under the original eIDAS regulation, fewer than half of EU member states formally notified a national eID scheme. Yet dozens of national, bank-operated and private schemes are in daily use, each with different protocols, assurance levels and registration requirements. Across the EU, 52% of people used an eID last year: from 99% in Denmark to 10% in Romania. But the harder question isn’t which schemes exist. It’s which ones people actually use.
IDENTIFICATION ACTIONS · ITSME, BELGIUM, 2024
MODEL: Bank-backed
IN PRACTICE: Belgians use itsme to log into their bank, sign contracts and reach government services, every day. That daily habit is what drives adoption.
ADULTS WHO HAVE EVER USED IT · GERMANY, SINCE 2010
MODEL: Government-issued, built into every ID card
IN PRACTICE: Germans can use their national eID for banking and government services. Most never do due to the complex setup, and that few portals accept it.
Access isn’t equal either
Some schemes you integrate with directly. Some are only reachable through a licensed broker, or closed to foreign entities altogether. We navigate that on your behalf.
" height="13.523999999999987px" id="WgxiaHFK_" transform="translate(21.195 21.6)" width="13.480975609756001px"/><path d="M 27.496 12.117 L 35.336 2.834 L 41.45 7.931 L 33.602 17.225 L 45.614 15.12 L 47 22.93 L 35.001 25.033 L 45.555 31.088 L 41.565 37.956 L 31.005 31.898 L 35.176 43.287 L 27.677 45.999 L 23.504 34.607 L 19.33 46 L 11.831 43.288 L 16.003 31.896 L 5.44 37.957 L 1.449 31.089 L 12.01 25.03 L 0 22.926 L 1.386 15.116 L 13.406 17.222 L 5.559 7.93 L 11.673 2.832 L 19.515 12.119 L 19.515 0 L 27.496 0 Z M 25.416 17.805 L 21.592 17.805 L 18.672 20.24 L 18.008 23.978 L 19.918 27.265 L 23.502 28.562 L 27.086 27.266 L 28.992 23.985 L 28.326 20.231 Z" fill="rgb(77, 85, 235)" height="46px" id="txBdfulm4" transform="translate(4 5.5)" width="47px"/><path d="M 17.751 4.494 C 17.575 4.243 17.384 4.002 17.179 3.775 C 16.546 3.026 15.816 2.363 15.008 1.805 C 14.548 1.491 14.064 1.212 13.561 0.971 C 12.484 0.448 11.323 0.119 10.131 0 C 9.906 0 9.682 0 9.458 0 C 9.234 0 8.987 0 8.734 0 C 8.09 0.046 7.452 0.159 6.831 0.338 C 6.281 0.495 5.746 0.699 5.232 0.949 C 4.727 1.192 4.243 1.476 3.785 1.798 C 2.998 2.358 2.283 3.013 1.657 3.746 C 1.462 3.991 1.259 4.242 1.071 4.508 C 0.663 5.094 0.305 5.712 0 6.356 C 0.303 6.984 0.667 7.581 1.085 8.139 C 1.263 8.391 1.456 8.631 1.664 8.858 C 2.295 9.61 3.025 10.273 3.835 10.829 C 4.294 11.145 4.778 11.424 5.282 11.663 C 5.801 11.913 6.341 12.117 6.896 12.274 C 7.514 12.454 8.15 12.564 8.792 12.605 C 9.016 12.605 9.241 12.605 9.465 12.605 C 9.689 12.605 9.935 12.605 10.189 12.605 C 10.829 12.559 11.462 12.445 12.077 12.267 C 12.63 12.115 13.166 11.908 13.677 11.648 C 14.183 11.411 14.667 11.129 15.124 10.807 C 15.912 10.248 16.627 9.594 17.251 8.858 C 17.447 8.614 17.649 8.362 17.83 8.103 C 18.208 7.53 18.538 6.927 18.814 6.299 C 18.518 5.665 18.162 5.061 17.751 4.494 Z M 9.407 9.808 C 8.708 9.809 8.025 9.604 7.443 9.22 C 6.862 8.835 6.408 8.288 6.14 7.646 C 5.871 7.005 5.8 6.3 5.936 5.619 C 6.071 4.937 6.407 4.312 6.9 3.82 C 7.394 3.329 8.023 2.994 8.708 2.858 C 9.394 2.722 10.104 2.791 10.75 3.056 C 11.395 3.322 11.947 3.771 12.336 4.349 C 12.724 4.926 12.931 5.604 12.931 6.299 C 12.932 6.759 12.842 7.215 12.665 7.641 C 12.488 8.067 12.229 8.453 11.902 8.779 C 11.574 9.105 11.186 9.364 10.757 9.54 C 10.329 9.717 9.871 9.808 9.407 9.808 Z" fill="rgb(133, 220, 255)" height="12.604578338990901px" id="iDBgIlY8f" transform="translate(18.902 21.6)" width="18.814364618065497px"/></svg>)
" width="47.99999957316186px"><path d="M 0 22.413 L 15.898 22.413 L 15.898 26.148 L 0 26.148 Z M 0 14.942 L 15.898 14.942 L 15.898 18.677 L 0 18.677 Z M 0 7.471 L 15.898 7.471 L 15.898 11.206 L 0 11.206 Z M 0 0 L 15.898 0 L 15.898 3.735 L 0 3.735 Z" fill="rgb(188, 255, 138)" height="26.14806391231275px" id="uUErnDcWH" transform="translate(16.051 12.607)" width="15.897580922521684px"/><path d="M 0 22.413 L 15.898 22.413 L 15.898 26.148 L 0 26.148 Z M 0 14.942 L 15.898 14.942 L 15.898 18.677 L 0 18.677 Z M 0 7.471 L 15.898 7.471 L 15.898 11.206 L 0 11.206 Z M 0 0 L 15.898 0 L 15.898 3.735 L 0 3.735 Z" fill="rgb(0, 204, 122)" height="26.14806388244631px" id="oUNeXKroM" transform="translate(16.051 8.872)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.4896692194004117px" id="gqY7lP2rL" transform="translate(16.051 7.471)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.489669190947893px" id="Kb5TfQmRb" transform="translate(16.051 11.206)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.4896692478529303px" id="ZAN1NVQ6D" transform="translate(16.051 14.942)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.489669190947893px" id="L9SOU9phH" transform="translate(16.051 18.677)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="pst5OoWkC" transform="translate(16.051 22.413)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.4896691909477795px" id="eVjB4iIpo" transform="translate(16.051 26.148)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="zlRZNmlUp" transform="translate(16.051 29.884)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.489669190947893px" id="EgfQlfkPt" transform="translate(16.051 33.619)" width="15.897580922521684px"/><path d="M 31.795 11.206 C 31.795 11.895 28.236 12.451 23.847 12.451 C 19.456 12.451 15.898 11.895 15.898 11.206 C 15.898 10.518 19.456 9.961 23.847 9.961 C 28.237 9.961 31.795 10.518 31.795 11.206 Z M 0 7.471 L 15.898 7.471 L 15.898 11.206 L 0 11.206 Z M 0 0 L 15.898 0 L 15.898 3.735 L 0 3.735 Z" fill="rgb(188, 255, 138)" height="12.45114647061098px" id="sPntWXb4t" transform="translate(0 27.549)" width="31.795162012984974px"/><path d="M 0 7.471 L 15.898 7.471 L 15.898 11.206 L 0 11.206 Z M 0 0 L 15.898 0 L 15.898 3.735 L 0 3.735 Z" fill="rgb(0, 204, 122)" height="11.206312909047483px" id="MSNxYKH3W" transform="translate(0 23.813)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="XuL6roUFd" transform="translate(0 22.413)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.4896691909477795px" id="zVgqIL_dg" transform="translate(0 26.148)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="D7JQPJIki" transform="translate(0 29.884)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.489669190947893px" id="SskSTDq50" transform="translate(0 33.619)" width="15.897580922521684px"/><path d="M 15.898 33.619 C 15.898 34.307 12.339 34.864 7.948 34.864 C 3.558 34.864 0 34.307 0 33.619 C 0 32.931 3.559 32.374 7.948 32.374 C 12.339 32.374 15.898 32.931 15.898 33.619 Z M 31.796 29.884 L 47.694 29.884 L 47.694 33.619 L 31.796 33.619 Z M 31.796 22.413 L 47.694 22.413 L 47.694 26.148 L 31.796 26.148 Z M 31.796 14.942 L 47.694 14.942 L 47.694 18.677 L 31.796 18.677 Z M 31.796 7.471 L 47.694 7.471 L 47.694 11.206 L 31.796 11.206 Z M 31.796 0 L 47.694 0 L 47.694 3.735 L 31.796 3.735 Z" fill="rgb(188, 255, 138)" height="34.86377273709047px" id="yj2NJa0J0" transform="translate(0 5.136)" width="47.6936605581418px"/><path d="M 0 29.884 L 15.898 29.884 L 15.898 33.619 L 0 33.619 Z M 0 22.413 L 15.898 22.413 L 15.898 26.148 L 0 26.148 Z M 0 14.942 L 15.898 14.942 L 15.898 18.677 L 0 18.677 Z M 0 7.471 L 15.898 7.471 L 15.898 11.206 L 0 11.206 Z M 0 0 L 15.898 0 L 15.898 3.735 L 0 3.735 Z" fill="rgb(0, 204, 122)" height="33.61893878803255px" id="rmtX4FFZo" transform="translate(32.102 1.401)" width="15.897580922521684px"/><path d="M 15.898 8.716 C 15.898 9.404 12.34 9.961 7.949 9.961 C 3.559 9.961 0.001 9.404 0.001 8.716 C 0.001 8.027 3.56 7.471 7.949 7.471 C 12.34 7.471 15.898 8.027 15.898 8.716 Z M 15.898 1.245 C 15.898 1.933 12.34 2.49 7.949 2.49 C 3.559 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.949 0 C 12.34 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="9.960544482614523px" id="z7warPbn9" transform="translate(32.102 0)" width="15.898498108318108px"/><path d="M 15.898 8.716 C 15.898 9.404 12.339 9.961 7.948 9.961 C 3.558 9.961 0 9.404 0 8.716 C 0 8.027 3.559 7.471 7.948 7.471 C 12.339 7.471 15.898 8.027 15.898 8.716 Z M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="9.96054449684084px" id="uOqEDZeNI" transform="translate(32.102 3.735)" width="15.897580922521684px"/><path d="M 15.898 8.716 C 15.898 9.404 12.339 9.961 7.948 9.961 C 3.558 9.961 0 9.404 0 8.716 C 0 8.027 3.559 7.471 7.948 7.471 C 12.339 7.471 15.898 8.027 15.898 8.716 Z M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="9.960544511067042px" id="fRbExKTbt" transform="translate(32.102 7.471)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.489669190947893px" id="alg42HxXC" transform="translate(32.102 18.677)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="D01rZ0qAj" transform="translate(32.102 22.413)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.4896691909477795px" id="gPVlsFpjX" transform="translate(32.102 26.148)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="uYIfykPp3" transform="translate(32.102 29.884)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(0, 204, 122)" height="2.489669190947893px" id="SQss0qMuY" transform="translate(32.102 33.619)" width="15.897580922521684px"/><path d="M 15.898 1.245 C 15.898 1.933 12.339 2.49 7.948 2.49 C 3.558 2.49 0 1.933 0 1.245 C 0 0.557 3.559 0 7.948 0 C 12.339 0 15.898 0.557 15.898 1.245 Z" fill="rgb(188, 255, 138)" height="2.489669190947893px" id="oWFixygN6" transform="translate(32.102 37.354)" width="15.897580922521684px"/></g></svg>)
" width="45px"><path d="M 0 0 L 13.333 0 L 13.333 4.167 L 0 4.167 Z" fill="rgb(0, 204, 122)" height="4.166666666666629px" id="tjydVv_o4" transform="translate(18.333 22.5)" width="13.333333333333258px"/><path d="M 0 13.333 L 0 0 L 4.167 0 L 4.167 13.333 Z" fill="rgb(0, 204, 122)" height="13.333333333333258px" id="VXWcIreuo" transform="translate(18.333 13.333)" width="4.166666666666629px"/><path d="M 37.168 12.568 C 39.158 15.497 40.218 18.959 40.212 22.5 C 40.212 32.283 32.283 40.213 22.5 40.213 C 12.717 40.213 4.788 32.283 4.788 22.5 C 4.788 12.718 12.717 4.788 22.5 4.788 C 24.525 4.788 26.469 5.127 28.282 5.753 L 29.76 1.197 C 27.422 0.402 24.969 -0.003 22.5 0 C 10.073 0 0 10.073 0 22.5 C 0 34.927 10.073 45 22.5 45 C 34.927 45 45 34.927 45 22.5 C 45 18.358 43.881 14.478 41.929 11.145 Z" fill="rgb(9, 62, 60)" height="45.000013485359204px" id="s0KhoANpL" width="45px"/><path d="M 0 3.75 C 0 1.679 1.679 0 3.75 0 C 5.821 0 7.5 1.679 7.5 3.75 C 7.5 5.821 5.821 7.5 3.75 7.5 C 1.679 7.5 0 5.821 0 3.75 Z" fill="rgb(0, 204, 122)" height="7.5px" id="K2NM8ptse" transform="translate(31.667 2.5)" width="7.5px"/></g></svg>)
" height="17.142857142857146px" id="FHuHBbRwU" transform="translate(8 30.857)" width="39.40298507462694px"/><path d="M 0 0 L 19.701 22.857 L 39.403 0 Z" fill="rgb(77, 85, 235)" height="22.857142857142854px" id="A4SxBwItk" transform="translate(8.597 8)" width="39.40298507462694px"/></svg>)
Biometric Authentication
Confirms the person presenting the eID is the person it belongs to at onboarding and every time they come back.
AML Screening and Monitoring
Sanctions, PEP and adverse media checks at onboarding, then continuously throughout the customer relationship; triggered by list updates, re-screening schedules, or risk events.
Qualified Electronic Signature
QES is another AMLR default route alongside eID and the EUDI Wallet, and the one that works today in every market, including those where a usable national eID scheme isn't yet live. If you're onboarding across Europe now, QES is how you stay compliant while eID adoption builds.
AMLR Readiness
A practical guide to what changes on 10 July 2027: which routes become default, what documentation you'll need for fallback methods, and what to put in place before the deadline.